analysis & case studies
HOW ARE PALM OIL TRADERS & REFINERS PERFORMING?
The first WWF–ZSL Palm Oil Traders & Refiners Index assesses 15 major companies against 100 environmental, social and governance indicators. It examines the evidence companies provide on their commitments, how they implement them and the progress they report across their palm oil supply chains.
The results show that sustainability policies and governance arrangements are widely established. However, the evidence becomes less consistent when companies are asked to demonstrate the coverage of their traceability systems, identify the volumes assessed for environmental and human rights risks, or quantify their engagement with suppliers.
The average company score is 58.8%, with scores ranging from 33.1% to 85.1%. Governance and grievances is the highest-scoring category, while traceability and supply-chain mapping is the lowest.
Traders and refiners occupy an influential position between producers and downstream markets. Their purchasing decisions, supplier requirements and support programmes can affect practices across extensive sourcing networks. POTRI’s findings highlight where these companies can provide stronger evidence that their commitments reach the full scope of their business and lead to action when problems arise.
15
COMPANIES ASSESSED
in the 2026 palm oil TRADERS & REFINERS scorecard
58.8%average company score
from33.1%
TO85.1%
Understanding the findings
POTRI scores reflect evidence against defined assessment criteria. Companies can receive full, partial or zero points, depending on factors such as the scope, detail and recency of the information provided.
Higher scores indicate stronger evidence against the framework. They do not certify that a company’s operations or supply chain are free from environmental or social harm.
100indicatorsacross10categories
Share of applicable points earned by category, all 15 companies
| Category | All indicators | Organisation | Policy | Practice |
|---|---|---|---|---|
| Sustainability policy and leadership | 78.7 | 76.6 | 90.0 | 91.7 |
| Traceability and supply-chain mapping | 37.3 | 53.2 | 24.0 | 49.9 |
| Certification standards | 62.7 | 63.8 | 82.8 | 45.9 |
| Deforestation, conversion and biodiversity | 54.7 | 60.0 | 49.2 | 61.7 |
| HCV, HCS and impact assessments | 67.8 | 81.2 | 60.0 | 68.2 |
| Peat, fire and GHG emissions | 61.0 | 74.1 | 53.8 | 64.7 |
| Water, chemicals and waste | 63.3 | 25.0 | 50.0 | 71.7 |
| Human rights and labour | 69.4 | 100.0 | 56.4 | 77.8 |
| Supplier engagement and smallholders | 51.5 | 23.3 | 39.1 | 65.7 |
| Governance and grievances | 90.6 | 100.0 | 90.0 | 86.8 |
FROM COMMITMENT TO ACTION
The green represents the companies that make a commitment; the orange represents those that provide measured evidence of delivering on it. What stays green is the gap between what is promised and what is shown.
RSPO certification
15companies are RSPO members0companies report 100% certified sourcing
Deforestation
15companies commit to zero deforestation4companies report the volume assessed for risk
Human rights
14companies have a human rights commitment3companies report the volume assessed for risk
Suppliers
15companies prioritise tier 1 suppliers5companies report the share of tier 1 suppliers engaged
KEY FINDINGS
Commitments & implementation
1Commitments need clearer evidence of implementation
Policies provide an essential foundation for responsible sourcing. They establish expectations for suppliers and help companies communicate the standards they intend to uphold in their supply chains. Their value depends on how consistently companies implement them.
These groups cover different indicators, so the difference does not measure the proportion of commitments implemented. It nevertheless highlights a recurring finding: companies generally provide stronger evidence of their intentions than of the extent and results of their actions.
What companies should do
Connect commitments to defined responsibilities, measurable coverage and documented responses to non-compliance. Explain which parts of the supply chain systems cover, where gaps remain and how they will be addressed.
66.0%of applicable points earned for policies & commitments
Policies and commitments66.0%
Monitoring, reporting & verification57.7%
Implementation52.9%
Share of applicable points earned, all 15 companies.
Traceability
2Traceability reporting needs to cover the full business
Traceability helps companies understand where their supply originates and where they need to investigate environmental or social risks. For integrated traders and refiners, reporting needs to capture the complexity of both activities.
Several companies report high traceability percentages, but those figures do not always clearly cover all relevant products, sourcing regions or trading operations. A percentage covering selected refineries or one country cannot establish the traceability of a company’s entire refining and trading business. Reporting solely on products that pass through company facilities may leave uncertainty about volumes traded without physical possession.
Traceability alone does not demonstrate sustainable production. It provides information companies need to assess risk, investigate concerns and support corrective action.
What companies should do
State the denominator behind each traceability percentage and whether it includes all relevant geographies, third-party supply, indirect sourcing and trading activities. Distinguish traceability to mills from traceability to plantations.
37.3%
of applicable points for traceability and supply-chain mapping, the lowest-scoring of the 10 categories
Reported traceability figures often cover only part of the chain: selected refineries, one country, or volumes that pass through company facilities. Companies should state the denominator behind each percentage.
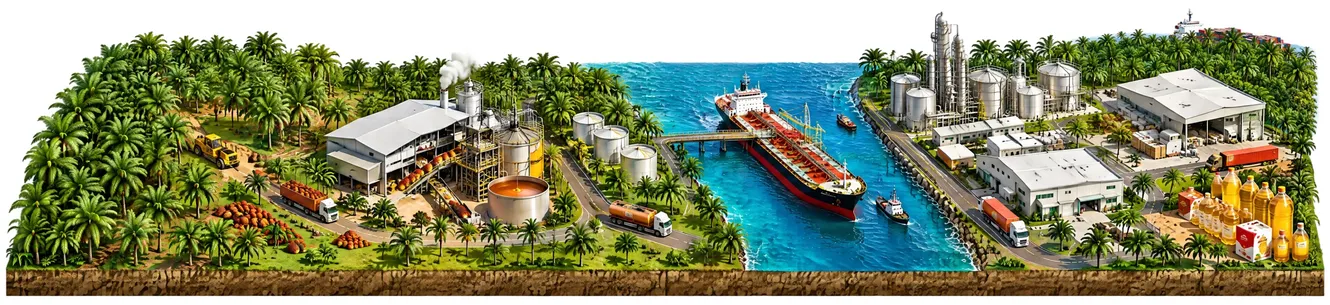
- Plantations
- Mills
- Storage & transport
- Shipping & trading
- Refineries
- Products
37.3% traceability & supply-chain mapping58.8% average company score, all categories
Certification
3RSPO membership needs to translate into greater certified sourcing
RSPO membership is widespread among the assessed companies: all 15 receive full points for membership. However, this level of participation does not translate into comparable uptake of certified palm oil.
The simple average of the companies’ reported RSPO uptake percentages is 20.9%, and none reports 100% uptake. Membership demonstrates participation in a certification system, while uptake shows the proportion of reported volumes sourced as certified. A credible sourcing plan needs to connect the two through clear milestones and transparent progress reporting.
What companies should do
Explain the barriers to increasing certified sourcing and the steps taken to overcome them. Distinguish between certification supply-chain models so buyers and financial institutions understand what sourcing figures represent.
20.9%average reported RSPO uptake. None reports 100%
RSPO membership15 of 15
15 full, 0 partial and 0 without points, of 15 companiesTime-bound plan for 100% RSPO-certified sourcing4 of 15
4 full, 0 partial and 11 without points, of 15 companies
Deforestation & conversion
4Protection needs to extend beyond forests
Avoiding deforestation is central to responsible palm oil sourcing. Protecting other natural ecosystems requires an explicit commitment to avoiding conversion as well.
All 15 companies receive points for a supplier zero-deforestation commitment, 11 of them full points. For zero conversion, 12 receive points, but only four receive full points for a commitment explicitly covering all natural ecosystems and all suppliers. Target dates are less widely evidenced: ten companies receive points for a zero-deforestation target date in supplier operations, compared with only three for zero conversion.
Although 14 receive points for a methodology for assessing deforestation- and conversion-free volumes, only four receive points for reporting the volume or percentage of sourcing assessed for deforestation and conversion risk.
What companies should do
Clearly identify the ecosystems and suppliers policies cover, establish cut-off dates and set deadlines for compliance. Explain both the assessment approach and its coverage.
4of 15full points for zero conversion across all ecosystems and suppliers
Zero-deforestation commitment11 full · 4 partial
11 full, 4 partial and 0 without points, of 15 companiesZero-conversion commitment4 full · 8 partial
4 full, 8 partial and 3 without points, of 15 companiesTarget date, zero deforestation10 of 15
10 full, 0 partial and 5 without points, of 15 companiesTarget date, zero conversion3 of 15
3 full, 0 partial and 12 without points, of 15 companiesVolume assessed for deforestation & conversion risk4 of 15
4 full, 0 partial and 11 without points, of 15 companies
Peat, fire & monitoring
5Monitoring needs a clear response when problems emerge
Monitoring can identify possible deforestation, conversion and other concerns. Its effectiveness depends on what companies do with the information.
These measures are relevant to managing forest, peat and fire risks. However, a commitment or monitoring system does not by itself demonstrate that a company has prevented harm or resolved an identified problem.
What companies should do
Explain how alerts are investigated, how affected suppliers are engaged and how corrective action is decided. Reporting should show how cases progress, what outcomes are sought and how completion is verified.
Full points across the 15 companies
Monitoring can flag possible deforestation, conversion and fire risk. Fewer companies show how they respond when an alert comes in.
7 of 15
Response process for alerts
7 full, 0 partial and 8 without points, of 15 companies9 of 15
Monitoring deforestation or conversion in supplier operations
9 full, 0 partial and 6 without points, of 15 companies11 of 15
Zero-burning commitment covering all suppliers
11 full, 0 partial and 4 without points, of 15 companies
Human rights
6Human rights commitments need stronger risk assessment
Human rights commitments are widely disclosed: 14 companies receive full points for their commitment. Evidence of comprehensive supply-chain risk assessment is less developed.
Seven companies receive partial points for making a supply-chain human rights risk assessment available, and none receives full points. Only three receive points for reporting the volume or percentage of supply assessed for human rights risk.
What companies should do
Explain whose rights are considered, the risks identified and the parts of the supply chain assessed, then connect those findings to prevention, mitigation and remedy.
0of 15full points for a supply-chain human rights risk assessment
Human rights commitment14 of 15
14 full, 0 partial and 1 without points, of 15 companiesSupply-chain risk assessment available7 partial
0 full, 7 partial and 8 without points, of 15 companiesVolume assessed for human rights risk3 of 15
3 full, 0 partial and 12 without points, of 15 companies
Supplier engagement
7Supplier accountability needs evidence of coverage and follow-through
Supplier accountability requires companies to establish expectations, identify where support is needed and demonstrate how they respond to non-compliance.
All 15 companies receive points for processes to prioritise Tier 1 suppliers for engagement and assessment, and for re-entry criteria for suspended suppliers. Reporting becomes more limited when examining non-compliance: five report the percentage of non-compliant suppliers and the associated share of volume, and only three report the percentage of non-compliant suppliers engaged in improvement plans.
There is evidence of support further upstream: 14 companies receive points for engagement with Tier 2 and other upstream suppliers, including six receiving full points. The central gap is between describing an engagement process and showing how extensively it operates.
What companies should do
Report who is engaged, what proportion of the supplier base this represents and how improvement plans address identified problems.
5of 15report the share of Tier 1 suppliers engaged on requirements
Process to prioritise Tier 1 suppliers15 of 15
15 full, 0 partial and 0 without points, of 15 companiesShare of Tier 1 suppliers engaged5 of 15
5 full, 0 partial and 10 without points, of 15 companiesNon-compliant suppliers and share of volume5 of 15
5 full, 0 partial and 10 without points, of 15 companiesNon-compliant suppliers in improvement plans3 of 15
3 full, 0 partial and 12 without points, of 15 companiesEngagement with Tier 2 and upstream suppliers6 full · 8 partial
6 full, 8 partial and 1 without points, of 15 companies
Smallholders
8Smallholder support needs responsible purchasing practices
Smallholder inclusion is an important area of commitment for these large global traders and refiners. Thirteen companies receive full points for a commitment to smallholder inclusion, while 11 receive full points for a programme supporting independent smallholders.
However, only one receives full points for a commitment to responsible purchasing practices that support upstream producer livelihoods and fair value distribution. Five others receive partial points. Support programmes can help producers meet sourcing requirements, but purchasing practices also shape their ability to do so.
What companies should do
Explain how commercial relationships support the producers companies source from, alongside training or other programme activities, and connect smallholder inclusion to how palm oil is purchased and value distributed.
Full points across the 15 companies
Most companies commit to smallholder inclusion and run support programmes. Only one shows purchasing practices that share value with the producers it buys from; five more receive partial points.
13 of 15
Commitment to smallholder inclusion
13 full, 0 partial and 2 without points, of 15 companies11 of 15
Programme supporting independent smallholders
11 full, 0 partial and 4 without points, of 15 companies1 of 15
Responsible purchasing practices that support producer livelihoods and fair value distribution
1 full, 5 partial and 9 without points, of 15 companies
Landscapes
9Landscape collaboration needs transparent reporting on contributions and results
Environmental and social challenges often extend beyond individual supply chains. Landscape and jurisdictional initiatives can bring companies together with governments, communities and other organisations to address shared concerns.
Qualifying participation can include financial or technical support, restoration, supplier engagement, monitoring and other implementation activities. This is an encouraging area of activity.
Participation should complement action within companies’ own sourcing networks. It cannot substitute for addressing gaps in traceability, supplier compliance or responsible purchasing.
What companies should do
Identify the initiatives supported, explain the company’s role and report progress against agreed objectives.
10of 15full points for landscape or jurisdictional initiatives
Active participation or substantive support10 full · 2 partial
10 full, 2 partial and 3 without points, of 15 companies
What needs to happen next?
Traders & refiners
Strengthen the connection between commitments and the evidence on supply-chain coverage and implementation. Priorities include comprehensive traceability reporting, clear environmental and social targets, quantified supplier engagement and transparent reporting on corrective action.
Downstream buyers
Use the findings to examine the coverage of their suppliers’ policies and systems.
Financial institutions
Use the assessments to identify questions for due diligence, stewardship and client engagement, and to establish measurable expectations for progress.
POTRI’s first assessment provides a baseline for more focused engagement with major palm oil traders and refiners. Progress will depend on demonstrating where requirements apply, how suppliers receive support and what happens when companies identify harm or non-compliance.